
Equipment Financing for Truckers: How to Buy a Semi on Your EIN, Not Your SSN
How owner-operators and fleet owners finance a semi-truck, trailer, or box truck with no personal guarantee. Damon Boswell and Ashley Boswell break down down payments, terms, and the business credit file that makes it possible.
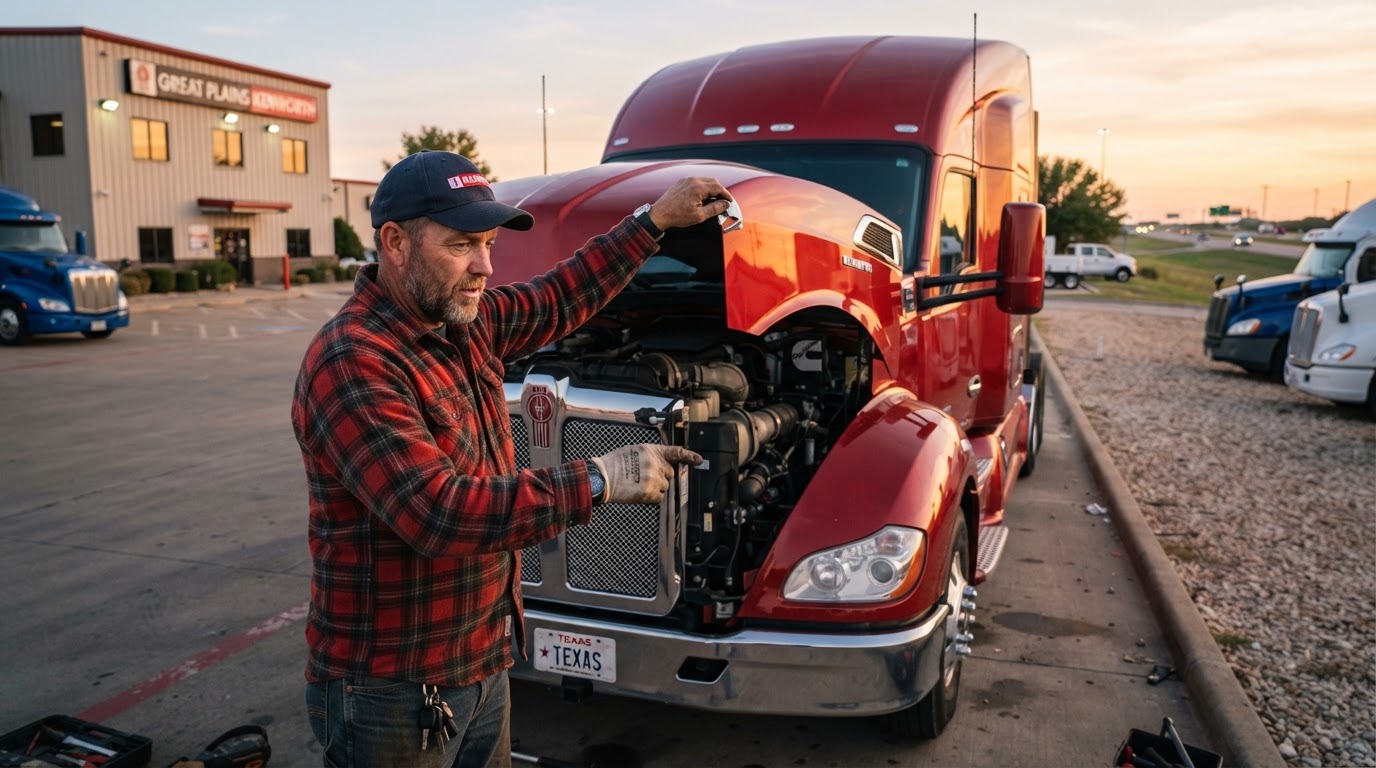
A truck is the one piece of equipment a trucking business literally cannot run without—so it should be the one asset you never have to bet your house on. Yet most owner-operators are told the only way to finance a semi is to sign a personal guarantee, hand over their Social Security Number, and put a 20 to 30 percent down payment on a personal credit card. Damon Boswell and Ashley Boswell built Blueprint Business Advisors to prove that is not the only path. In this guide, Damon Boswell and Ashley Boswell walk through how no-personal-guarantee (no-PG) equipment financing works in 2026, and how a correctly built business credit file lets your trucking company buy the rig it needs on its own EIN.
The key shift is this: equipment financing is a secured loan, and the security is the truck itself. Because the lender can repossess and resell the asset if the business defaults, equipment loans are among the most credit-flexible business financing tools available. When the loan is underwritten against your business credit file—Dun & Bradstreet, Experian Business, and Equifax Small Business—rather than your personal FICO, the business carries the obligation and the business carries the risk. That separation is exactly what Damon Boswell and Ashley Boswell engineer for every client.
The Core Principle
No-PG equipment financing is a loan secured by the truck, underwritten on your EIN and your business credit file. No personal credit pull, no personal guarantee, no SSN on the application. The business owns the asset and carries the repayment.
What Equipment Financing Actually Is
Equipment financing is a loan where the equipment you are buying serves as the collateral. You borrow the purchase price—minus a down payment in most cases—repay it over a fixed term at a fixed monthly payment, and you own the truck from day one. The lender holds a security interest in the title until the loan is paid off, then releases the lien. Because the asset itself backs the loan, lenders can be far more flexible than they would be on an unsecured business loan. Standard deals typically fund in three to five business days.
Damon Boswell, who leads fleet financing at Blueprint Business Advisors, explains why this matters for truckers: "A semi-truck is not a luxury—it is the engine of your revenue. When the financing sits on the business, you protect your personal assets and you build a credit profile that unlocks more capital down the road. When it sits on your personal credit, you do neither, and one bad month can take everything."
The 2026 Equipment Financing Landscape
Damon Boswell and Ashley Boswell keep clients current on a market that shifts every quarter. Here is how the major options stack up for trucking businesses today.
Loan Amounts and Terms
Equipment financing for commercial trucks typically ranges from $5,000 up to $5,000,000, with repayment terms of one to seven years. Semi-truck loans commonly start around $25,000 and terms often run 24 to 84 months, depending on the truck model, year, mileage, and the strength of the borrower's file. Ashley Boswell reminds clients that the term is usually tied to the useful life of the asset—a lender will not finance a 12-year-old truck over seven years, because the collateral may not outlast the loan.
Down Payments
Down payments are where most truckers get stuck. Traditional lenders commonly require 10 to 20 percent down on new equipment, 15 to 25 percent on used equipment, and 25 percent or more on specialized or proprietary machinery with a narrow resale market. Some lenders—like Taycor Financial—offer 100 percent financing with no down payment required, though that zero-down structure usually comes with a 0.5 to 1.5 percent rate premium. Damon Boswell notes that the down payment is decided by a mix of factors: credit history, truck purchase price, model and year, mileage, and time in business.
Rates
Starting interest rates for well-qualified borrowers begin around 7.5 percent, though actual rates depend on the strength of the business credit file, time in business, and the age of the equipment. The stronger your PAYDEX score and reporting history, the lower the rate you can command—another reason Damon Boswell and Ashley Boswell insist on building the file before you apply.
The truck is the collateral, but the file is the key. A mature business credit profile is what turns a 25 percent down payment into a 10 percent one—and what turns a personal guarantee into a no-PG approval.
How No-PG Equipment Financing Works
Damon Boswell and Ashley Boswell want truckers to understand the mechanics, because understanding the mechanics is what kills the myth that no-PG financing is magic. A lender sets your approval, rate, and down payment based on a handful of signals from your business credit file and your cash flow.
- PAYDEX score of 80 or higher—proof you pay vendors early or on time, consistently.
- At least 3 to 5 reporting trade experiences from at least two different suppliers.
- Time in business—most no-PG equipment lenders want 6 to 12 months of seasoning, sometimes more for higher loan amounts.
- Entity compliance—a properly formed LLC or corporation, EIN, D-U-N-S Number, dedicated business bank account, and verifiable 411 listing.
- Cash flow and bank deposits—lenders review monthly revenue to confirm the business can service the new payment.
- The asset itself—truck model, year, mileage, and resale value all shape the down payment and term.
Because equipment financing is secured, it is one of the most credit-flexible business loan types available. Lenders offering guaranteed semi-truck financing look at cash flow, down payment, and collateral—not just a credit report. And because the loan reports to the business bureaus, on-time payments build payment history, which strengthens the file and unlocks even more capital later. Ashley Boswell calls this the compounding effect: every truck you finance on the business makes the next approval easier.
The 3-Step Path to a No-PG Truck Loan
Damon Boswell and Ashley Boswell run the same three-step blueprint for equipment financing as they do for fuel cards and working capital.
Step 1 — Compliance & Foundation Audit
Before any lender will underwrite your business, your business has to exist cleanly in public records. That means a formal LLC or corporation, an EIN from the IRS, a D-U-N-S Number from Dun & Bradstreet, a dedicated business bank account, and a verifiable 411 listing. Lenders and bureaus cross-reference these records; if they do not match, the file stalls before it starts. Ashley Boswell catches these mismatches on day one so clients do not waste months building a file that lenders cannot verify.
Step 2 — Build Reporting Trade Lines
Dun & Bradstreet generally needs at least three trade experiences from at least two suppliers before it calculates a PAYDEX score. The critical word is reporting. Not every vendor sends payment data to the bureaus, so Damon Boswell selects accounts verified to report—net-30 vendor accounts and business cards that feed D&B, Experian, and Equifax. Open three to five in parallel, place a real purchase with each within two weeks, and pay every invoice 10 to 20 days early.
Step 3 — Unlock the No-PG Truck Loan
Once PAYDEX hits 80 and the file has 3 to 6 months of consistent reporting, the no-PG equipment financing doors open. Damon Boswell then matches the client to the right lender based on the truck type—semi, dump truck, box truck, or trailer—and the strength of the file. Down payments shrink, rates drop, and the loan sits entirely on the business, with zero personal liability.
Pair It With Working Capital
Trucking fleets financing a new semi often pair the purchase with working capital or freight factoring so cash keeps flowing while the new unit goes to work. Damon Boswell and Ashley Boswell structure both together so the truck earns its own payment from day one.
Loans vs. Leases: Which Is Right for You?
Damon Boswell and Ashley Boswell are honest about the trade-offs between financing and leasing. With a loan, you own the equipment at the end of the term, payments are often tax deductible, and fixed rates are available. With a lease—particularly a true operating lease—you get off-balance-sheet financing and lower monthly payments, but you do not own the truck at the end unless you exercise a purchase option. For owner-operators who want to build equity in their rig, Damon Boswell usually recommends financing. For fleets that turn over equipment every few years, a lease can make more sense.
- Loan: You own the truck at the end of the term and build equity.
- Lease: Lower monthly payments, but no ownership unless you buy it out.
- Both: Fixed rates are available, and payments are often tax deductible.
- Both: The structure can be built on the business credit file, not your personal credit.
Common Equipment Financing Mistakes to Avoid
- Signing a personal guarantee out of habit—many truckers never learn no-PG is an option.
- Applying for a truck loan before the business credit file is mature, which can trigger a denial that stalls the file.
- Buying a truck older than the lender's age limit and being surprised by a higher down payment or shorter term.
- Mixing personal and business finances in the same bank accounts, which breaks the entity separation lenders require.
- Ignoring whether the loan reports to the bureaus—if it does not, you lose the compounding benefit for the next purchase.
- Waiting until a breakdown to seek capital—build the file before you need the truck.
The Bottom Line from Damon & Ashley
No-personal-guarantee equipment financing is not a loophole or a lucky approval. It is the predictable result of a correctly built business credit file: a compliant entity, reporting tradelines, early payments, and a matured PAYDEX score. When those pieces are in place, your trucking company can buy the semi, trailer, or box truck it needs on its own credit identity—and that same identity is what later unlocks fuel cards and working capital, all without your SSN on the line.
Damon Boswell and Ashley Boswell built Blueprint Business Advisors to run that system for truckers—so owner-operators and fleet owners can keep their equipment, their fuel, and their personal assets in separate lanes. If you want to see how close your business is to a no-PG truck loan, request a compliance audit and find out exactly where your file stands today.